Perception and Action in Financial Planning: An Interview with CPA Annie
Columnist Young Reporters Yangminxing Wu, Yangminyan Wu
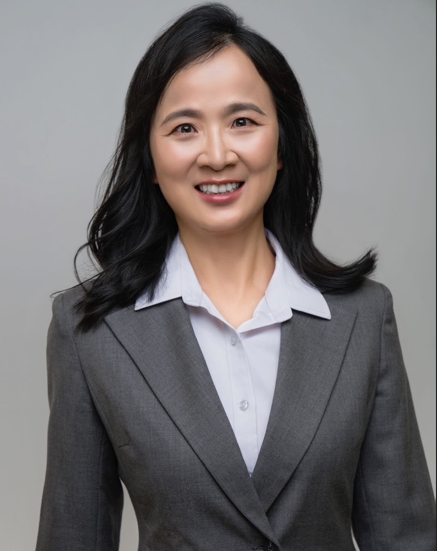
Annie’s financial background spans China and the United States. In an interview with Youth of We Chinese in America, she explained that she earned CPA qualifications in China, continued her studies in the United States, and earned CPA qualifications there as well. Rather than opening a practice centered on preparing tax returns, she hoped to work for a large company. She went on to spend many years at a Fortune Global 500 business.
Her original choice of a university major was less deliberate. At seventeen or eighteen, she recalled, she did not have a clear career direction, and her parents largely guided her decisions about school and field of study. Years of financial work later drew her attention to the people making the decisions: Why do some people understand what they should do but never begin? Why can the same opportunity mean different things to different people?
During the interview, Annie discussed tax and estate planning through those questions. She explored how people evaluate information, why families postpone difficult conversations, and how young people can begin developing financial judgment. Understanding the numbers in a proposal, she emphasized, is only one part of understanding how it fits a person’s life.
Finding information and understanding its conditions
Annie opened the conversation by asking why people with seemingly similar starting points and learning abilities can develop very differently over time. Beyond technical knowledge, she identified three factors: access to information, the ability to interpret it, and the willingness to act.
Access determines whether a person discovers an opportunity or learns about a rule. Interpretation involves understanding the conditions behind it. One person may notice only an attractive result, while another examines how that result became possible. Two people can therefore encounter the same tax strategy and reach different conclusions about its value.
That distinction matters when financial information spreads through social media. Advice about saving taxes or managing money may omit the circumstances that make it useful. A household must still consider its own income, assets, and needs before deciding whether someone else’s experience applies.
Annie also discussed how familiar cultural and personal experiences influence preferences. She pointed to the importance some Chinese families place on buying a home as an example of how a familiar asset can carry a strong sense of security. She encouraged young people to encounter other approaches and examine possibilities beyond their existing assumptions.
Even understanding an opportunity does not ensure action. Annie said she often hears people respond that they need more time to think, and that delay can continue.
“What ultimately widens the gap is often not who knows more, but who actually takes action,” she said.
Tax preparation and planning begin at different times
Asked about the difference between preparing a tax return and planning ahead, Annie introduced a traditional story about the Chinese physician Bian Que and his brothers.
In her account, Bian Que becomes well known for treating people who are already seriously ill. Yet he considers his brothers better physicians because they intervene while an illness is still mild or before it becomes apparent. Their preventive work attracts less recognition because people never experience the crisis it prevents.
Annie saw a similar challenge in financial planning. By filing season, most of the previous year’s income, expenses, and investment transactions have already occurred. Preparing a return focuses on organizing and reporting that information accurately. Planning allows people to consider consequences while decisions are still open.
Some options do remain after the end of a tax year. Eligible IRA contributions, for example, may still be made for the prior year by the applicable filing deadline. But different decisions have different deadlines, and waiting until filing season can mean that some opportunities have passed.
Annie wanted people to recognize the less visible value of prevention. A useful plan may help a family avoid having to solve a serious problem under pressure.
For students, she compared planning to preparing for an examination. Once the result is already recorded, there is limited value in asking how one should have studied. Financial decisions likewise deserve attention while there is still time to compare possibilities and make adjustments.
Changing established beliefs starts with trust
The interview also addressed people who expect this year’s tax refund to resemble last year’s, or arrive at a consultation with a strategy they found online. How should a conversation proceed when those expectations do not match the person’s circumstances?
Annie acknowledged that people are often particularly cautious about money. A brief conversation is unlikely to change beliefs developed over many years, and a clear explanation does not automatically lead to agreement.
She tries to combine an understanding of a person’s feelings with an analysis of the facts. Someone who hesitates repeatedly may understand the proposal but worry about risk, losing control, or whether to trust the person offering advice. Identifying that concern helps establish what actually needs to be discussed.
“It is a process of building trust,” she said.
Sometimes, she added, a person needs time even after an explanation. She compared this with conversations with her own child: a parent may offer repeated warnings, but the child may still want to try something and understand it through experience. An adviser can explain and remind, while recognizing that people are at different stages in their lives.
The concerns behind postponed estate planning
A family may understand the importance of estate planning and still postpone it for reasons more complicated than a busy schedule. Annie described older family members who fear that arranging their property means giving up authority or becoming less influential within the household.
Others find that the conversation brings them face to face with aging, illness, and death. In a family with several children, discussing property may also mean confronting different opinions and potential disputes over its distribution.
Unfamiliar concepts and paperwork create another obstacle. Someone may know that planning matters without knowing whom to contact or what to understand first. Fear of making a mistake can make leaving the issue alone feel easier.
These concerns help explain why repeatedly telling someone to act may not move the process forward. A person worried about losing control needs that concern understood. A person overwhelmed by complexity may need the task broken into clearer steps. Annie’s emphasis was on identifying the underlying concern before working through the practical choices.
Making room for important tasks before they become urgent
To explain how delay develops, Annie introduced the Eisenhower Matrix, which organizes tasks by importance and urgency. She focused on work that is important but does not demand immediate attention, such as maintaining health or reviewing family finances before a pressing problem appears.
These tasks can lose their place to daily demands because postponing them seems to have no immediate consequence. Left unresolved, however, a manageable question can become an urgent problem. A family then has less time to compare its options carefully.
Annie suggested dividing a large task into smaller questions and assigning time to each. A family might reserve one hour on the third Thursday of every month to review its arrangements. A task without an external deadline can still have a schedule.
During the interview, she asked whether high school students also have important but less urgent work. I mentioned improving academically and building relationships with teachers. Both require attention, even when tomorrow’s examination feels more immediate.
Annie then told a story about two fishermen who initially use inefficient methods to catch enough food. One begins spending additional time each day making a net. The work does not immediately increase his catch, but once the net is ready, it improves how efficiently he can fish. The other continues working in the same way.
She used the example to explain why some efforts deserve time before their benefits become visible. For students, continued learning and personal development can require that same deliberate commitment.
Looking beyond tax savings to everyday flexibility
A proposal may look attractive numerically while limiting a family’s future choices. Annie illustrated the difficulty with the decision to repay a mortgage.
Some people want to pay off their home quickly because complete ownership feels reassuring. But using all available cash to do so can leave a household with too little accessible money for an unexpected expense. Having an asset and having money available when it is needed are different considerations.
She compared financial arrangements to interlocking gears. Today’s tax position, future expenses, and access to funds affect one another. Concentrating on one result can hide costs elsewhere.
Annie also discussed arrangements used by some wealthy households involving borrowing against assets, postponing asset sales, and inherited-property basis adjustments. She noted that these methods may not suit ordinary households. The distinctions matter: loans carry interest and repayment obligations, falling collateral values can lead to demands for more collateral or asset sales, and inherited-property basis rules do not make every asset or every type of tax disappear.
Before discussing a particular tool, Annie wants to understand a client’s household, expectations, goals, and capacity for risk. Someone who cannot sleep after a small loss may need a different approach from someone willing and able to accept fluctuations, even if the same return comparison is presented to both.
“The numbers are static, but life is dynamic,” she said. She wants clients to understand the conditions a plan depends on, its expenses and restrictions, and the room available to adjust it later. Her aim is to help them notice overlooked questions and judge what serves their actual needs.
Young people have the advantage of starting earlier
For young people approaching their first work income, tax returns, and investments, Annie identified one belief she hopes to challenge: that financial planning belongs to adults or wealthy people and can wait until they earn more.
She used compounding to explain the role of time. When earnings remain invested, they have the opportunity to generate further earnings. To make the process easier to picture, she introduced the Rule of 72: dividing 72 by an assumed annual percentage return gives an approximate number of years for an amount to double.
At a hypothetical constant annual return of 4 percent, doubling would take approximately eighteen years. At 6 percent, it would take approximately twelve. These are simplified illustrations, not promises of stable returns. Actual results are affected by possible losses, taxes, fees, and inflation.
Annie also compared illustrations of starting contributions earlier and waiting many years to begin. Her emphasis was on the longer growth period available to the earliest contributions. Young people do not have to wait for an ideal income before learning and developing habits.
“You may not have much money now, but you have time that other people cannot buy,” she said.
Approaching unfamiliar questions with a growth mindset
Near the end of the interview, Annie returned to how people think. She introduced a growth mindset as the belief that abilities can develop through effort, effective strategies, and guidance, rather than being fixed from the beginning.
Someone encountering taxes or investing for the first time may find the concepts unfamiliar or interpret a mistake as evidence that they are unsuited to the subject. Annie encouraged students to treat difficulty as something they have not yet mastered, continue asking questions, and seek better ways to learn.
She considered this attitude relevant to evaluating information in the age of artificial intelligence. Easier access to answers still leaves people responsible for judging reliability and relevance. Understanding another person’s circumstances and making decisions under uncertainty also require attention beyond simply retrieving information.
Annie closed by offering to continue sharing with the reporter’s friends, school clubs, or peers interested in taxes, financial literacy, and ways of thinking. For young people, a first step could be as specific as choosing one unfamiliar question to investigate, then making room for the next step in their schedule.